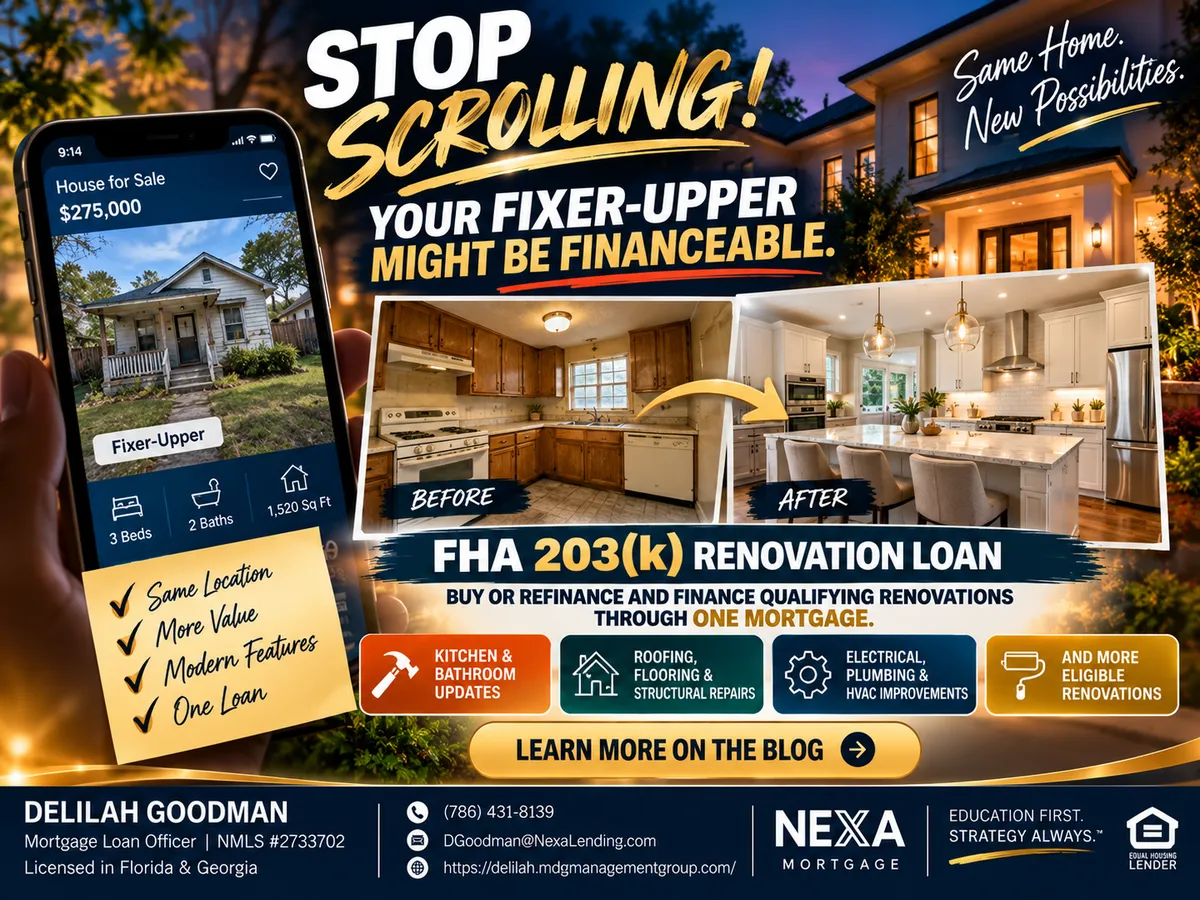
Before You Scroll Past That Fixer-Upper: How FHA 203(k) Financing Can Help You Purchase or Renovate a Home
That outdated kitchen, aging roof, or bathroom stuck in another decade might not be the dealbreaker you think it is.
Let's talk about something many homebuyers overlook while scrolling through real estate listings.
You've found a property in a neighborhood you love. The layout works, the backyard has potential, and the location checks nearly every box.
There's just one problem.
The house needs work.
Now you're wondering whether you should walk away or somehow find the money to make the improvements.
Before you eliminate that property from your search, there's a mortgage program worth understanding: the FHA 203(k) Rehabilitation Mortgage Insurance Program.
And it isn't just for people purchasing fixer-uppers. Eligible existing homeowners may also use the program to refinance and renovate their current residence.
1. What Is an FHA 203(k) Renovation Loan?
An FHA 203(k) loan is a government-insured mortgage program that allows eligible borrowers to finance a home's purchase or refinance along with qualifying rehabilitation expenses.
Instead of obtaining a traditional mortgage and separately arranging financing for the renovations, the program may allow you to combine eligible costs into one mortgage transaction.
That means you can evaluate the property's potential rather than looking exclusively at its current condition.
But remember, this is still a mortgage. Income, credit, property eligibility, project feasibility, and lender underwriting requirements apply.
2. What Types of Renovations May Qualify?
Depending on the specific project and FHA requirements, eligible improvements may include:
Kitchen and bathroom remodeling.
Roof replacement or repairs.
Flooring improvements.
Electrical and plumbing updates.
Heating and air-conditioning improvements.
Accessibility modifications.
Structural repairs and other eligible rehabilitation work.
Some projects may involve cosmetic modernization, while others address safety, functionality, or property-condition issues.
Not every improvement qualifies. Luxury additions and certain other projects may be excluded.
The key is understanding which improvements can be included before you make an offer or commit to a renovation budget.
3. There Are Two FHA 203(k) Programs
Limited 203(k)
This option generally accommodates smaller, less complex renovation projects.
HUD increased the Limited 203(k) rehabilitation-cost ceiling to $75,000 for eligible cases under its 2025 program changes.
That ceiling is not an automatic renovation allowance. Actual eligible costs, property requirements, and lender approval still determine what can be financed.
Standard 203(k)
This option is designed for more extensive rehabilitation projects, including eligible structural work.
Standard 203(k) projects generally require a minimum of $5,000 in rehabilitation costs and involve an FHA-approved 203(k) consultant.
The right program depends on the scope of work, not simply the price of the property.
4. Can You Use FHA 203(k) to Renovate a Home You Already Own?
Yes, potentially.
If you already own your primary residence, FHA 203(k) financing may provide a way to refinance your existing mortgage and finance eligible improvements.
For example, you might want to modernize an aging kitchen, address roofing issues, update essential systems, or make accessibility improvements.
However, refinancing replaces your existing mortgage. If you currently have a favorable interest rate, changing that loan could increase your borrowing costs.
Before refinancing, compare the proposed monthly payment, closing costs, interest rate, loan term, and total repayment expense.
Sometimes another renovation-financing option may be more appropriate.
5. How Does FHA 203(k) Financing Work?
Although every transaction is different, the process generally includes:
Step 1: Review your financing qualifications.
Determine whether your credit, income, available funds, and property goals align with FHA and lender requirements.
Step 2: Identify the property or renovation project.
Review the property's condition and proposed improvements.
Step 3: Establish the rehabilitation scope.
Obtain appropriate contractor proposals, required documentation, and consultant involvement when applicable.
Step 4: Complete the financing and property review.
The lender evaluates the loan, rehabilitation plan, appraisal, and other required documentation.
Step 5: Close and complete the approved work.
Renovation funds are administered under program requirements, with inspections and disbursements as applicable.
An FHA 203(k) project requires more coordination than a typical purchase mortgage. Contractor selection, documentation, inspections, and project deadlines all matter.
6. Can First-Time Homebuyers Use This Program?
Absolutely—first-time homebuyers may be eligible, but the program isn't limited to them.
FHA 203(k) financing generally supports eligible owner-occupied properties, including qualifying one- to four-unit homes.
For buyers who have been overlooking properties because they need improvements, this program may expand the range of homes worth evaluating.
It doesn't mean every fixer-upper is financeable.
It means you should understand the financing possibilities before automatically dismissing a property.
7. Why This Matters in Florida and Georgia
In both Florida and Georgia, buyers may encounter older homes that need roofing, plumbing, electrical, HVAC, or interior improvements.
An FHA 203(k) loan may be worth exploring when the property and rehabilitation plan meet applicable requirements.
Florida buyers should pay particular attention to insurance, permitting, roof condition, and local construction requirements.
Georgia buyers should likewise evaluate property condition, contractor availability, local permitting, and the overall renovation budget.
In either state, your mortgage strategy should account for the full housing payment, including taxes, insurance, mortgage insurance, and other applicable costs.
8. Before You Buy the Fixer-Upper, Ask These Questions
Is the property eligible for FHA 203(k) financing?
Are the proposed renovations permitted under the program?
How much cash will I need?
What will my monthly payment look like after financing the improvements?
What happens if the renovation costs exceed the original estimate?
And most importantly:
Does this property still make financial sense after accounting for the renovation budget and long-term ownership costs?
These are the conversations worth having before falling in love with a property's potential.
Your Dream Home May Need a Little Work—And a Better Financing Strategy
The next time you're scrolling through listings and find a house that needs updating, don't assume the only choices are paying cash for repairs or walking away.
There may be a third option worth exploring.
FHA 203(k) financing could help you see the opportunity behind the renovations.
But the program is not right for every borrower, property, or project.
Let's review your goals, financing qualifications, and proposed improvements before you make a decision.
Ready to explore your renovation financing options?
Message me RENOVATE to request an FHA 203(k) financing consultation.
Delilah Goodman
Mortgage Loan Officer | NMLS #2733702
Licensed in Florida & Georgia
Phone: (786) 431-8139
Email: [email protected]
Website: https://delilah.mdgmanagementgroup.com/
Education First. Strategy Always.™
Educational information only. FHA 203(k) financing is subject to applicable HUD requirements, lender participation, underwriting, property eligibility, approved rehabilitation costs, and loan approval. Financing terms and costs vary.