Hard Money Lending: The Investor's Shortcut—or an Expensive Lesson?
You've found a property listed below market value.
It needs some work, but the neighborhood is promising. You've watched enough renovation shows to recognize the potential, and you've already started imagining the finished product.
There's just one small problem.
You don't have the cash to purchase and renovate it.
Before you abandon the opportunity, somebody mentions hard money lending.
Now you're interested.
But before you start calculating your future profits, we need to have a conversation about what hard money actually is, how investors use it, and why the wrong financing strategy can turn a promising deal into a very expensive education.
1. What Exactly Is Hard Money Lending?
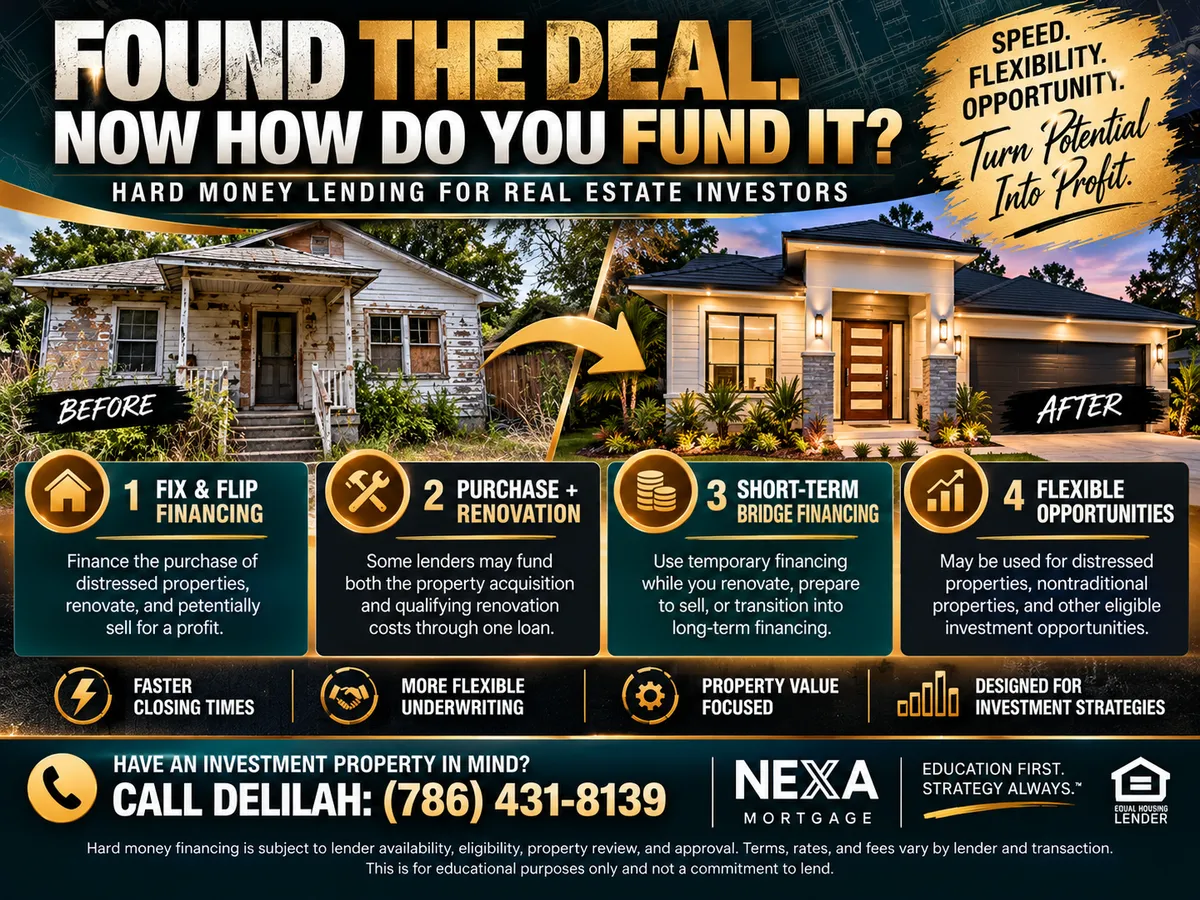
Hard money lending is a form of financing commonly used by real estate investors to purchase, renovate, or temporarily finance investment properties.
Unlike a traditional mortgage, which places significant emphasis on borrower income, credit, and long-term repayment ability, hard money financing typically focuses heavily on the property's value, available equity, project feasibility, and the investor's exit strategy.
These loans are commonly offered by private lenders or specialized investment lending companies.
Here's the distinction:
Traditional financing often asks: Can this borrower support the mortgage over time?
Hard money financing also asks: Does this property provide sufficient collateral, and how will this investor repay the loan?
Don't misunderstand that difference. Hard money lenders still evaluate borrowers, and requirements vary significantly.
2. Why Would an Investor Use Hard Money Instead of a Traditional Mortgage?
Because real estate opportunities don't always arrive neatly packaged.
Imagine finding a distressed property that needs substantial repairs before it can qualify for conventional financing.
Or discovering a potential investment with a short closing deadline.
Hard money may be worth exploring when an investor needs:
Short-term financing for an eligible investment property.
Acquisition and renovation capital.
Financing for a distressed or nontraditional property.
Bridge financing until permanent financing or a sale becomes possible.
A funding structure designed around a defined investment project.
But speed and flexibility come at a price.
Hard money loans commonly carry higher interest rates, upfront fees, and shorter repayment periods than conventional long-term mortgages.
The objective isn't simply getting the money. It's making sure the investment can afford the money.
3. Let's Talk About Fix-and-Flip Investing
This is where many new investors first encounter hard money.
Suppose you find a property that needs renovation.
Your plan is straightforward:
Purchase it, improve it, sell it, repay the lender, and keep the remaining profit.
Sounds simple, right?
Well, real estate has a habit of introducing expenses that weren't invited to the original business plan.
Construction delays. Permit issues. Insurance. Property taxes. Contractor changes. Unexpected repairs. And the possibility that your projected selling price was a little too optimistic.
That's why a successful fix-and-flip strategy starts with the numbers, not the paint colors.
4. A $200,000 Investment Example
Let's walk through a hypothetical project.
Project item | Amount |
|---|---|
Property purchase | $200,000 |
Renovation budget | $50,000 |
Total acquisition and renovation budget | $250,000 |
Estimated after-repair value (ARV) | $325,000 |
At first glance, the difference between $250,000 and $325,000 is $75,000.
And that's exactly where some inexperienced investors get themselves into trouble.
That $75,000 is not your profit.
You still need to account for financing costs, lender fees, insurance, taxes, utilities, closing costs, potential selling expenses, and unexpected construction costs.
Let's say your lender provides $200,000 at an illustrative 12% annual interest rate, with interest-only payments and a 9-month holding period.
That's approximately $2,000 per month in interest, or $18,000 over nine months, assuming the full balance remains outstanding.
And we haven't included origination points or other loan expenses.
Suddenly, that projected profit looks very different.
The lesson? A profitable-looking property isn't necessarily a profitable investment.
5. What Are Points, LTV, and ARV?
If you're going to explore hard money financing, learn these three terms.
Points: Upfront lender fees commonly expressed as a percentage of the loan amount. Two points on a $200,000 loan equal $4,000.
Loan-to-Value (LTV): The loan amount divided by the applicable property value. Lenders may calculate this using the purchase price, current appraised value, or another specified valuation basis.
After-Repair Value (ARV): The estimated market value of the property after the proposed renovations are completed.
Some lenders also use loan-to-cost (LTC), which compares financing to eligible project costs.
Understanding these calculations helps investors evaluate how much capital they may need to contribute.
6. The Most Important Part of Hard Money Lending: Your Exit Strategy
Let's talk about the part I wish every beginning investor would take seriously.
How are you paying this loan back?
Hard money is usually short-term financing.
That means the lender expects repayment within a defined period, often through a property sale, refinance, or another documented source.
An investor might plan to:
Sell the property. Complete the renovation and repay the loan from the sale proceeds.
Refinance the property. Transition into longer-term financing if the completed property, borrower, and rental income qualify.
Use another verified repayment source. This must be realistic and consistent with the lender's requirements.
If your entire plan depends on everything going perfectly, you don't have an adequate exit strategy.
You have a very optimistic calendar.
7. Can You Use Hard Money to Build a Rental Portfolio?
Potentially, yes.
Some investors use short-term acquisition and renovation financing before refinancing into a longer-term rental-property loan.
You may hear this discussed alongside the BRRRR strategy:
Buy → Rehab → Rent → Refinance → Repeat.
The concept is to improve a property, establish rental income, and explore whether refinancing can recover some invested capital.
But there's an important warning.
A refinance is never automatic.
The completed property must qualify under the new lender's requirements, which may include valuation, seasoning, loan-to-value limits, rental income, credit, reserves, and other underwriting conditions.
If the refinance doesn't work, you still have a short-term loan that must be repaid.
8. Five Questions to Ask Before Accepting Hard Money
Before signing, ask yourself:
1. What's my total cost of capital?
Include interest, points, lender fees, extension fees, and closing expenses.
2. How much cash must I contribute?
Understand the down payment, renovation funding, reserves, and expenses not covered by the lender.
3. How are renovation funds released?
Some lenders reimburse approved work through construction draws rather than advancing the entire renovation budget upfront.
4. What happens if my project takes longer?
Review maturity dates, extension options, default provisions, and potential additional costs.
5. What's my backup exit strategy?
Plan for a slower sale, lower appraisal, delayed renovation, or unsuccessful refinance.
Remember, being approved for a loan doesn't mean the investment itself is a good decision.
9. Is Hard Money Lending Right for Every Small Investor?
Absolutely not.
For some experienced investors with well-researched projects, sufficient reserves, reliable contractors, and realistic exit strategies, it can be a useful financing tool.
For someone purchasing their first investment property without a renovation budget, contingency funds, or a clear repayment plan, it may create unnecessary risk.
Hard money isn't free money.
It isn't a substitute for due diligence.
And it certainly isn't permission to purchase a property simply because the numbers look attractive on social media.
Financing should support the investment strategy—not become the strategy.
10. Before You Chase the Deal, Learn How to Structure It
One of the biggest advantages an investor can develop is the ability to evaluate opportunities before committing capital.
That means understanding acquisition costs, financing structures, renovation budgets, cash flow, project risks, and exit strategies.
It's also why I created the Real Estate Wealth Builder Academy.
The Academy is designed to help aspiring and developing investors build a stronger foundation in real estate investing, including financing concepts, evaluating opportunities, and developing investment strategies.
Because finding a property is only the beginning.
Knowing how to evaluate and structure the opportunity is where the real education starts.
Ready to Think Like an Investor?
If you're considering a fix-and-flip project, rental investment, or another real estate opportunity, begin with the numbers and the strategy.
📩 Message me INVEST to discuss investment financing options.
📚 Interested in learning more? Explore the Real Estate Wealth Builder Academy and begin building your investment knowledge.
Delilah Goodman
Mortgage Loan Officer | NMLS #2733702
Licensed in Florida & Georgia
📞 (786) 431-8139
📧 [email protected]
🌐 https://delilah.mdgmanagementgroup.com/
Education First. Strategy Always.™
This article is for educational purposes only. The examples are hypothetical and do not represent an actual loan offer, lender pricing, projected return, or guarantee of financing. Hard money lending may involve substantial financial risk, including foreclosure and loss of invested capital. Loan availability and terms vary by lender, property, and applicable law.