Hometown Hero
Florida Hometown Heroes Down Payment Assistance Program: What Homebuyers Need to Know in 2026
Updated August 2026
Buying a home in Florida can be challenging—especially when you have the income to afford a monthly mortgage payment but haven't accumulated enough cash for the down payment and closing costs.
That's where Florida's Hometown Heroes Housing Program may help.
The program is administered through the Florida Housing Finance Corporation and is designed to help eligible Florida workers and military members purchase a primary residence by providing significant down payment and closing-cost assistance.
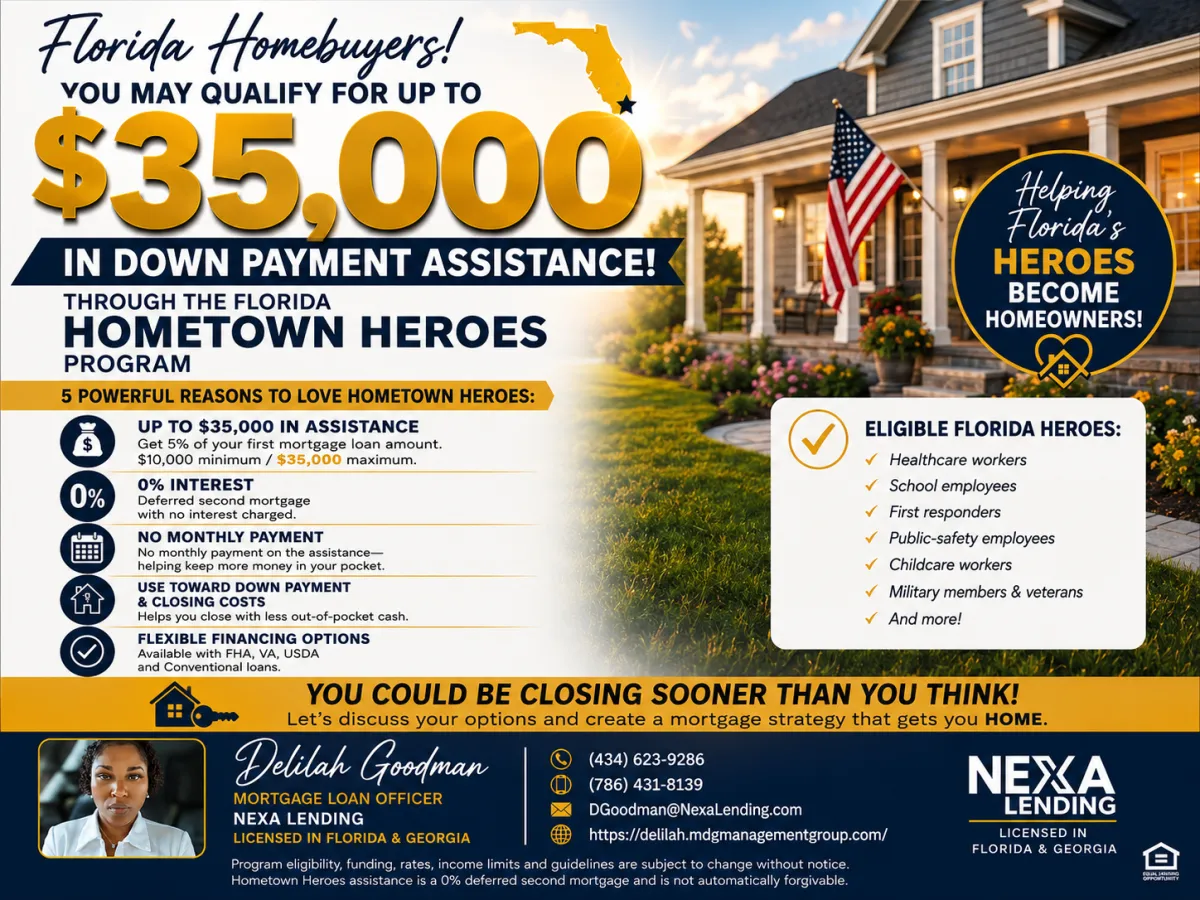
For qualifying buyers, Hometown Heroes can provide 5% of the first mortgage loan amount—generally from $10,000 up to $35,000.
But there's an important detail every buyer should understand:
Hometown Heroes assistance is not free money and it is not automatically forgiven.
It is generally provided through a 0% interest, deferred second mortgage.
Let's break down exactly how it works.
How Much Down Payment Assistance Can You Receive?
Eligible borrowers can receive assistance equal to:
5% of the first mortgage loan amount
Subject to:
Minimum assistance: $10,000
Maximum assistance: $35,000
0% interest
No regular monthly payment on the assistance
Deferred repayment
Non-amortizing
Not automatically forgivable
For example:
A $250,000 first mortgage could generate approximately $12,500 in assistance.
A $400,000 first mortgage could generate approximately $20,000.
A $600,000 first mortgage could generate approximately $30,000.
Once the calculation reaches the program maximum, assistance is capped at $35,000.
So when you hear that Hometown Heroes offers "up to $35,000," remember that borrowers don't automatically receive $35,000. The actual assistance is calculated from the first mortgage amount.
Who Can Qualify for Hometown Heroes in 2026?
This is particularly important because the program has changed over the years.
Older information online may describe Hometown Heroes as being available broadly to Florida's full-time workforce.
The 2026 program has specific occupational eligibility requirements.
Qualifying categories identified by Florida Housing include certain:
Healthcare workers
School employees
First responders
Public safety employees
Court employees
Childcare workers
U.S. military servicemembers
Military reservists
U.S. Coast Guard members and reservists
Florida National Guard members
Veterans meeting applicable employment requirements
Your occupation and employment should therefore be reviewed before assuming you qualify.
Do You Have to Be a First-Time Homebuyer?
Generally, yes.
For Florida Housing purposes, a first-time homebuyer is generally someone who hasn't owned and occupied a primary residence during the previous three years.
However, there is an important exception for certain:
Veterans and active-duty military servicemembers.
This means a qualifying veteran or active-duty servicemember may potentially participate even if they previously owned a home.
What Can Hometown Heroes Money Be Used For?
Hometown Heroes assistance is designed to help with the upfront costs associated with purchasing a home.
That can include eligible:
Down payment expenses
and
Closing costs.
This can be extremely valuable for a buyer who earns enough income to qualify for the mortgage but doesn't want—or isn't able—to drain savings to get through closing.
Is the $35,000 a Grant?
No.
This is one of the biggest misconceptions about Hometown Heroes.
The assistance is generally structured as a 0% deferred second mortgage.
That means you normally aren't making monthly principal-and-interest payments on the Hometown Heroes assistance.
However, the money may eventually have to be repaid.
The outstanding balance generally becomes due when certain events occur, including situations such as:
Selling the home
Refinancing the first mortgage
Transferring ownership
Renting the property
No longer occupying it as your required primary residence
For example, imagine receiving $20,000 in Hometown Heroes assistance.
You live in the house for five years and later decide to sell.
The outstanding Hometown Heroes balance would generally be repaid as part of that transaction.
Because the assistance carries 0% interest, you aren't accumulating years of interest on that deferred balance.
What Mortgage Programs Can Be Used?
Hometown Heroes can work with eligible Florida Housing first mortgages, including options involving:
FHA
Popular with buyers who may benefit from flexible credit and down-payment requirements.
VA
A powerful option for eligible veterans and servicemembers that may allow 100% financing under applicable VA guidelines.
USDA
Available for qualifying borrowers and eligible properties and potentially offering 100% financing.
Conventional
Florida Housing also offers qualifying conventional first-mortgage options.
The right program depends on much more than the lowest down payment.
As your mortgage professional, my job is to compare the total financing structure—including payment, mortgage insurance, cash required, assistance, repayment requirements and long-term strategy.
What Credit Score Do You Need?
Florida Housing's Homebuyer Loan Program generally establishes a:
640 minimum credit score.
However, having a 640 score doesn't automatically mean you're approved.
You still have to qualify for the underlying mortgage.
Depending on the loan program, underwriting may consider:
Credit history
Debt-to-income ratio
Employment
Income
Assets
Mortgage payment
Property eligibility
Automated underwriting findings
FHA, VA, USDA or conventional guidelines
This is why I recommend completing a mortgage eligibility review instead of trying to determine eligibility from your credit score alone.
Are There Income Limits?
Yes.
Hometown Heroes is an income-restricted housing program.
Applicable income and loan limits can vary based on factors including the Florida county where you're purchasing and the mortgage program being used.
This means someone purchasing in Broward County shouldn't necessarily use the same qualifying figures as someone buying in another Florida county.
Income limits should be checked against the current Florida Housing guidelines when you're preparing to purchase.
Do You Have to Live in the Home?
Yes.
Hometown Heroes is intended for the purchase of a primary residence.
It isn't designed to finance:
Vacation homes
Second homes
Traditional investment properties
Occupancy is particularly important because renting or otherwise ceasing to use the property as your required primary residence may affect repayment of the Hometown Heroes assistance.
What About Manufactured Homes?
Qualifying manufactured homes may potentially be eligible.
Florida law includes provisions for certain manufactured homes constructed after July 13, 1994, subject to program, property, title, permanent-affixation and underlying mortgage requirements.
Manufactured-home transactions require additional property review, so eligibility should be evaluated before making an offer.
Homebuyer Education Is Part of the Process
Florida Housing's homebuyer programs generally require approved homebuyer education.
Don't think of this as simply another box to check.
Homebuyer education can help you understand:
The mortgage process
Budgeting
Closing costs
Homeownership expenses
Insurance
Property taxes
Maintaining your home
Your responsibilities after closing
I strongly believe mortgage education should happen before you get to the closing table—not after.
One Hometown Heroes Rule Buyers Often Overlook: Refinancing
This is important.
Imagine purchasing a home with:
$400,000 first mortgage
and
$20,000 Hometown Heroes assistance.
Two years later, mortgage rates fall significantly and you want to refinance.
Because refinancing is generally a repayment-triggering event, that $20,000 Hometown Heroes balance may have to be addressed as part of the refinance.
That's why I don't believe buyers should look at down payment assistance only in terms of:
"How much money can I get today?"
We also need to ask:
"How will this financing structure affect me tomorrow?"
A good mortgage strategy considers both.
Hometown Heroes Isn't Always the Only DPA Option
Florida Housing has other homebuyer assistance programs as well.
Depending on the borrower's circumstances, alternatives can include programs such as FL Assist, FL HLP and qualifying HFA conventional assistance options.
Some programs offer less assistance.
Some have different repayment structures.
Some may offer forgivable assistance under applicable conditions.
And some may make more financial sense depending on how long you expect to own the home or whether you expect to refinance.
Bigger assistance doesn't automatically mean better financing.
The right question is:
Which mortgage and assistance combination puts you in the strongest financial position?
That's the comparison I want my borrowers to make.
Hometown Heroes Funding Is Limited
Another important consideration is that Hometown Heroes operates with limited program funding.
Florida has previously seen available Hometown Heroes allocations become fully committed.
That means being eligible for the program doesn't necessarily guarantee that assistance will be available when you're ready to purchase.
There are really two separate questions:
1. Do you qualify for Hometown Heroes?
and
2. Is funding available and able to be reserved for your transaction?
That's why buyers interested in the program should begin preparing before finding the house.
Should You Use Hometown Heroes?
For the right buyer, Hometown Heroes can be an excellent homeownership tool.
Imagine having good employment, sufficient income and acceptable credit—but being short on the $15,000, $20,000 or $30,000 needed between your down payment and closing costs.
Assistance could potentially bridge that gap.
But I don't recommend choosing a mortgage simply because someone advertises:
"Get up to $35,000!"
Your financing needs to make sense as a complete package.
We should evaluate:
Purchase price + first mortgage + interest rate + mortgage insurance + taxes + homeowners insurance + HOA + DPA + cash to close + future repayment obligations = Your Real Homeownership Strategy.
That's how I approach mortgage planning.
Before You Start Shopping, Let's Find Out What You Actually Qualify For
If you're a Florida homebuyer and believe you may qualify for Hometown Heroes, don't wait until you're under contract to find out.
I can help you review:
Occupational eligibility
First-time-homebuyer eligibility
Credit
Income
Debt-to-income ratio
County income limits
FHA, VA, USDA and Conventional options
Estimated purchasing power
Down payment requirements
Closing costs
Potential Hometown Heroes assistance
Other available down payment assistance options
Then we can compare your options and build a strategy around what you can comfortably afford, not simply the maximum amount a lender might approve.
Education First. Strategy Always.
Delilah Goodman
Mortgage Loan Officer
NEXA Lending
Licensed in Florida & Georgia
Office: (434) 623-9286
Cell: (786) 431-8139
[email protected]
delilah.mdgmanagementgroup.com
Program availability, funding, rates, income limits, loan limits and eligibility requirements are subject to change. Down payment assistance is subject to qualification and available program funding. Hometown Heroes assistance is generally provided as a 0% deferred second mortgage and is not automatically forgivable. This information is for educational purposes and is not a commitment to lend.
Sources & Further Information
Program information should always be verified against the current guidelines published by the Florida Housing Finance Corporation and applicable Florida law before a borrower relies upon Hometown Heroes assistance for a purchase transaction.