HUD & FHA UPDATES
WHAT CURRENT HUD & FHA UPDATES COULD MEAN FOR YOUR HOMEOWNERSHIP PLAN
Updated September 2026
If you're currently renting but hope to purchase a home, here's something I want you to understand:
Your preparation for homeownership doesn't begin when you find a house. It begins while you're still renting.
The way you pay your rent, manage your credit, save your money, handle debt and prepare your financial documents can all play a role in your eventual mortgage application.
And there are several HUD and FHA developments that future buyers should know about.
Let's break them down.
YOUR RENTAL PAYMENT HISTORY MAY BE MORE IMPORTANT THAN YOU REALIZE
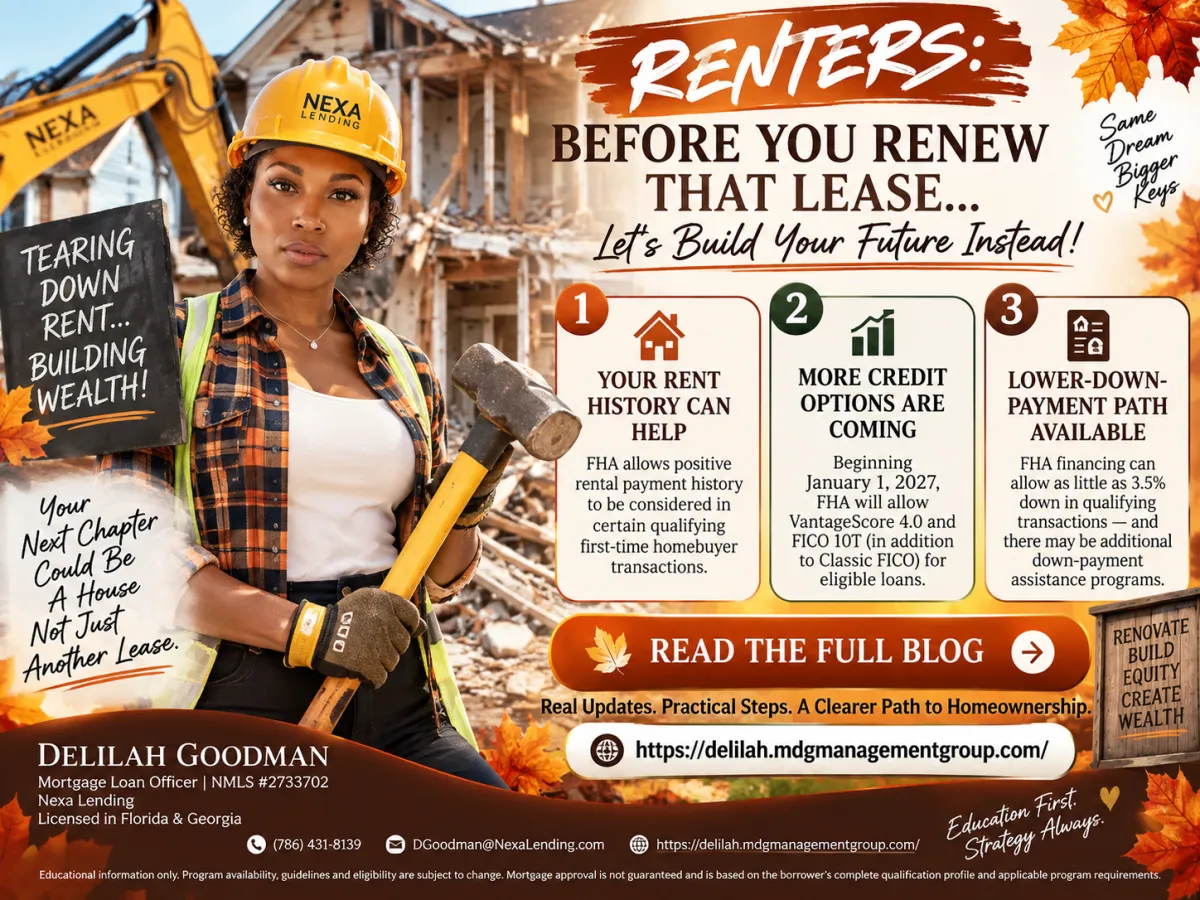
One of the most important FHA policies for renters is the ability for lenders to identify positive rental payment history in FHA's TOTAL Mortgage Scorecard for certain first-time homebuyer purchase transactions.
Under current FHA guidance, positive rental payment history generally means that all rental payments during the previous 12 months were made within the month they were due.
There are specific requirements.
For this feature of FHA's TOTAL Mortgage Scorecard, the transaction must be a purchase, at least one borrower must qualify as a first-time homebuyer under FHA's definition, the Minimum Decision Credit Score must be at least 620, and at least one borrower must have documented positive rental history with monthly rent of $300 or more for the previous 12 months.
Acceptable documentation can include the lease plus qualifying verification such as bank or payment-service statements, canceled checks, qualifying landlord verification or a rental-management-company reference.
What does that mean for renters?
Start treating your rent payments as part of your future mortgage preparation.
Pay consistently.
Pay through a method that creates a paper trail whenever possible.
Keep your lease.
Keep your bank statements.
Keep records of electronic rent payments.
And don't assume that because you've paid rent every month, your lender will automatically be able to use that information in every mortgage scenario.
The loan program, underwriting method and your complete financial profile still matter.
FHA IS NOT THE SAME THING AS HUD — AND FHA DOESN'T GIVE YOU A MORTGAGE DIRECTLY
This is another misconception I hear from future buyers.
HUD is the U.S. Department of Housing and Urban Development. FHA is the Federal Housing Administration and operates within HUD.
FHA generally does not lend the money directly to a homebuyer. Instead, FHA provides mortgage insurance on qualifying loans originated by approved lenders.
That distinction matters because you'll still need to qualify for the mortgage.
Your income, employment, credit profile, debts, assets, property, loan structure and other applicable underwriting requirements must be reviewed.
FHA CAN OFFER A LOWER-DOWN-PAYMENT PATH — BUT DOWN PAYMENT ISN'T THE WHOLE STORY
FHA financing can permit financing up to 96.5% of a property's value in qualifying transactions, which is why you frequently hear FHA described as having a 3.5% minimum required investment.
But please don't make the mistake of thinking:
“If I save 3.5%, I'm ready to buy.”
There can be considerably more to prepare for.
Depending on the transaction, buyers may need funds for items such as inspections, appraisal-related expenses, closing costs, prepaid expenses, homeowners insurance and reserves.
There may also be eligible assistance, gifts, seller contributions or other permitted sources that can change the cash-to-close calculation.
That's why we calculate the whole transaction, not just the down payment.
YOUR CREDIT OPTIONS ARE ALSO CHANGING
FHA announced another significant development in September 2026.
Beginning with applicable FHA Title II forward mortgage case numbers assigned on or after January 1, 2027, FHA's TOTAL Mortgage Scorecard is scheduled to allow VantageScore 4.0 and FICO Score 10T, in addition to Classic FICO, as eligible credit-score models.
Why should a renter preparing to buy care about that?
Because mortgage credit evaluation continues to evolve.
But I want to be very clear about what this does not mean.
It does not mean everyone's mortgage score will increase.
It does not mean credit requirements disappear.
And it does not guarantee mortgage approval.
Your complete credit and financial profile will still matter.
The best strategy is therefore not to wait for a new scoring model to “fix” your credit.
Prepare the fundamentals now.
FHA IS ALSO REVIEWING ITS PROPERTY REQUIREMENTS
On September 22, 2026, FHA announced proposed updates to its Minimum Property Requirements for FHA-insured mortgages.
The goal is to modernize and reorganize standards and better align them, where practical, with current industry practices.
However, here's the important word:
PROPOSED.
These aren't rules that buyers should begin treating as finalized requirements today.
FHA has specifically stated that its existing policies remain in effect until amended.
That's an important lesson whenever you see a headline saying mortgage guidelines are “changing.”
A proposal, announcement and implemented underwriting guideline are three different things.
HUD HAS ALREADY MADE OTHER FHA CHANGES DURING 2026
In June 2026, HUD announced 14 FHA Single Family policy changes designed to reduce administrative burdens, lower certain costs and improve program efficiency.
Those changes covered areas ranging from appraisal field reviews and mortgagee requirements to Limited 203(k) rehabilitation financing and other operational requirements.
For future buyers, the larger takeaway is simple:
Mortgage programs aren't static.
Guidelines, processes and opportunities change.
That is one reason getting mortgage-ready should involve reviewing your situation under the guidelines available when you're actually preparing to purchase.
DON'T WAIT UNTIL 30 DAYS BEFORE YOUR LEASE EXPIRES
This may be the most important part of this entire conversation.
If you know you'd eventually like to purchase a home, don't wait until your landlord sends you a renewal notice to begin preparing.
Ideally, I want to have the conversation months before your lease expires.
That gives us time to review:
• Your credit profile
• Income and employment
• Current monthly obligations
• Rental history
• Available assets
• Savings
• Estimated cash to close
• Potential loan programs
• Possible down-payment-assistance opportunities
• Your desired housing payment
• Your target purchase timeframe
And if something isn't ready yet?
That's valuable information too.
We can identify the issue before you're under contract.
“I PAY $2,500 IN RENT, SO I CAN AFFORD A $2,500 MORTGAGE.”
Not necessarily.
This is one of the most important concepts I teach future buyers.
Your mortgage payment isn't the only cost we need to evaluate.
Your total housing expense may include principal and interest, property taxes, homeowners insurance, mortgage insurance when applicable, HOA or condominium assessments and other property-related expenses.
And homeownership introduces expenses that renters may not currently pay directly, including maintenance and repairs.
So instead of asking:
“Can I buy a house for the same amount I'm paying in rent?”
Let's ask:
“What complete housing payment fits comfortably into my financial plan, and what purchase price and loan structure could support it?”
That's a much better conversation.
WHAT ABOUT DOWN-PAYMENT ASSISTANCE?
For some qualifying buyers, down-payment or closing-cost assistance may be available through state, local or other eligible programs.
But assistance isn't automatically available to every buyer.
Programs can have their own requirements regarding income, purchase price, location, occupancy, homebuyer education, loan type, available funding and other eligibility criteria.
That's why I don't want you building your entire purchase plan around an assistance program you haven't been evaluated for.
We first determine what you qualify for and then identify programs that may complement your mortgage strategy.
SHOULD YOU RENEW YOUR LEASE — OR START PREPARING TO BUY?
Before automatically signing another 12-month lease, ask yourself:
When does my current lease expire?
How much am I paying in rent?
How much have I saved?
What does my credit profile currently look like?
Do I have stable and documentable income?
What monthly housing payment would actually be comfortable?
Am I carrying balances that could affect qualification?
Do I have documentation showing my rental-payment history?
And most importantly:
Have I actually spoken with a mortgage professional to find out where I stand?
You don't have to be ready to purchase tomorrow to have that conversation.
Sometimes the result is:
You're closer than you thought.
Other times, it's:
We need six months.
Either answer is more useful than guessing.
YOUR RENTER-TO-HOMEBUYER PLAN
If buying a home is one of your goals, here's where I recommend beginning:
6–12 months before your target purchase: Review credit, income, debts, savings and rental history.
3–6 months before: Address identified qualification issues, continue documenting rent, build savings and evaluate potential mortgage and assistance programs.
Before shopping: Complete a mortgage review/preapproval as appropriate and establish a realistic purchase range and total housing-payment target.
Before making an offer: Review the specific property's taxes, insurance, HOA/condo expenses and other factors that could affect financing and affordability.
Don't just prepare to find a house.
Prepare to become a homeowner.
EDUCATION FIRST. STRATEGY ALWAYS.
If you're currently renting in Florida or Georgia and homeownership is on your radar, you don't need to figure everything out alone.
Let's review where you are now, identify where you want to go and determine what needs to happen between the two.
You may be ready now.
You may need several months.
Either way, having a strategy gives you something far more valuable than guessing:
A roadmap.
Delilah Goodman
Mortgage Loan Officer | NMLS #2733702
Nexa Lending
Licensed in Florida & Georgia
(786) 431-8139
[email protected]
Educational information only. Mortgage programs, underwriting requirements, interest rates, assistance-program availability and eligibility requirements are subject to change. Loan approval is not guaranteed and depends on the borrower's complete qualification profile and applicable program requirements.