Treasury Is Doubling Long-Term Bond Buybacks — What Could This Mean for Mortgage Rates?
Treasury Is Doubling Long-Term Bond Buybacks — What Could This Mean for Mortgage Rates?
If you are planning to buy a home, refinance, invest in real estate, or simply waiting for mortgage rates to improve, there is an important Treasury market development worth understanding.
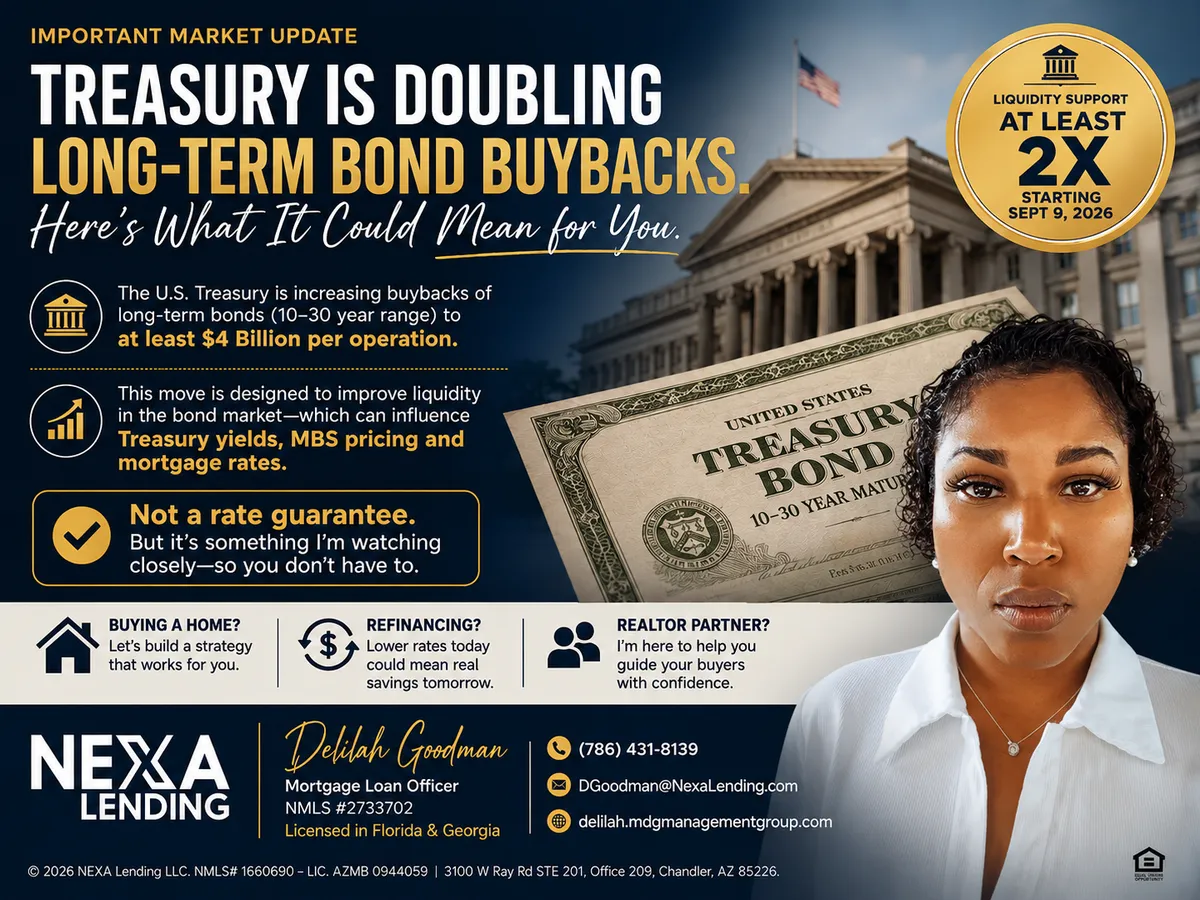
The U.S. Department of the Treasury announced that beginning September 9, 2026, it will at least double the maximum size of certain liquidity-support buyback operations involving longer-term Treasury securities.
The current maximum of $2 billion per operation will increase to at least $4 billion for certain Treasury securities in the 10-to-20-year and 20-to-30-year sectors.
That sounds extremely technical—but there is a reason I am bringing it to your attention.
Because what happens in the Treasury and bond markets can eventually influence mortgage-backed securities (MBS), lender pricing, and the mortgage rates available to homebuyers and homeowners.
First: What Is Treasury Actually Doing?
Think of the Treasury market like an inventory system.
The U.S. government regularly issues new Treasury notes and bonds. As newer securities enter the market, older Treasury securities may become less actively traded.
Treasury's buyback program allows market participants to sell certain eligible older Treasury securities back to the government.
Until now, Treasury's maximum purchase size for these particular long-term operations has been approximately:
$2 Billion Per Operation
Beginning September 9, that increases to:
At Least $4 Billion Per Operation
In other words, Treasury is becoming a significantly larger buyer of certain older long-term government securities.
The primary purpose is liquidity support—helping the Treasury market operate more efficiently and making it easier for market participants to buy and sell these securities.
Does This Mean the Government Is Trying to Lower Mortgage Rates?
Not exactly.
And this distinction is important.
This announcement should not be interpreted as the Federal Reserve cutting interest rates or beginning another round of quantitative easing.
The Treasury Department and Federal Reserve have very different responsibilities.
Treasury is primarily managing federal government financing and the Treasury securities market.
The Federal Reserve controls monetary policy and the federal funds rate.
What Treasury is doing here is essentially managing the liquidity and composition of outstanding government debt.
However, there is an important connection to mortgages.
Why Am I Watching This as a Mortgage Loan Officer?
Mortgage rates do not simply move because the Federal Reserve raises or lowers the federal funds rate.
Mortgage pricing is heavily influenced by the bond market—particularly mortgage-backed securities and longer-term Treasury yields.
A simplified version looks like this:
Treasury Market
↓
10-Year Treasury Yield
↓
Mortgage-Backed Securities (MBS)
↓
Lender Pricing
↓
Mortgage Rates Available to Borrowers
This is why you may occasionally see mortgage rates improve even when the Federal Reserve hasn't changed rates.
The bond market is constantly reacting to inflation, employment, economic growth, Treasury supply, investor demand, Federal Reserve expectations, and other economic information.
Could These Treasury Buybacks Help Mortgage Rates?
Potentially—but there are no guarantees.
Generally speaking, when demand for bonds increases:
Bond Prices Rise → Bond Yields Fall
Declining longer-term Treasury yields can create a more favorable environment for mortgage-backed securities and mortgage pricing.
Increasing Treasury's purchases in longer-duration securities could therefore provide some technical support to the bond market.
But I want to be very clear:
This announcement does NOT mean mortgage rates are automatically going down.
There are much larger economic forces affecting mortgage rates.
Inflation could come in higher than expected.
Employment data could surprise the market.
Investors could demand higher yields.
The Federal Reserve could change expectations regarding future monetary policy.
Treasury issuance could increase.
Any of those factors could push Treasury yields—and potentially mortgage rates—higher despite the expanded buyback program.
That is why I view this announcement as one piece of a much larger mortgage-rate puzzle.
What Should Homebuyers Take From This?
If you have been waiting for the "perfect rate" before purchasing a home, I would caution against making your entire homeownership decision based on predictions about where rates might go.
Instead, we should evaluate the numbers that actually apply to your financial situation.
That includes:
Your purchase price
Down payment
Credit profile
Debt-to-income ratio
Available loan programs
Seller concessions
Down-payment assistance eligibility
Property taxes and insurance
Mortgage insurance
Available interest rate and financing structure
Your expected monthly payment
A headline about Treasury bonds cannot tell you whether you personally are ready to purchase a home.
Your numbers can.
What Should Current Homeowners Take From This?
This is also something I will be watching for homeowners who purchased or refinanced when mortgage rates were higher.
If Treasury yields and mortgage-backed securities eventually move favorably enough to create better mortgage pricing, certain homeowners could have opportunities to evaluate refinancing.
But refinancing should never be based solely on the fact that "rates dropped."
We have to compare:
Current Mortgage vs. Proposed Mortgage
and determine whether the savings justify the costs associated with refinancing.
The goal is not simply obtaining a lower interest rate.
The goal is improving your overall financial position.
What Should Realtors Take From This?
For my Realtor partners, developments like this are another reason I encourage you to avoid telling buyers:
"Just wait until rates come down."
Nobody can guarantee exactly when that will happen.
Instead, let's determine whether the buyer can comfortably purchase today and then structure the financing appropriately.
If rates improve significantly later, refinancing may become an option.
If rates increase, the buyer may be glad they secured their financing when they did.
And if rates decline while they are actively shopping, we can evaluate the available pricing at that time.
Education first. Strategy always.
What Am I Watching Next?
For me, the Treasury announcement isn't the finish line.
It's another market signal.
I will continue watching:
10-Year Treasury Yields • Mortgage-Backed Securities • Inflation Data • Employment Reports • Federal Reserve Policy • Treasury Supply • Lender Pricing
The important question isn't simply:
"Did Treasury increase its bond buybacks?"
The better question is:
"How is the bond market reacting—and is that reaction actually translating into better mortgage pricing?"
That is where the opportunity for borrowers may ultimately appear.
My Message to Buyers, Homeowners & Realtors
There is going to be a tremendous amount of information circulating about interest rates, the Federal Reserve, Treasury bonds, inflation, and the housing market.
Some headlines will sound extremely positive.
Others will sound extremely negative.
My job is to help you understand what those headlines actually mean for your mortgage strategy.
If you are considering purchasing, refinancing, investing, or simply preparing for homeownership, you do not have to wait for the news to tell you when you are ready.
We can evaluate your numbers, understand your options, and create a strategy based on your actual financial position.
Because in mortgage lending:
The headline matters. Your numbers matter more.
Education First. Strategy Always.
Delilah Goodman
Mortgage Loan Officer | NMLS #2733702
NEXA Lending
Licensed in Florida & Georgia
Cell: (786) 431-8139
Email: [email protected]
Website: https://delilah.mdgmanagementgroup.com